
In the FT, Richard Milne reports about Marvin Goodfriend and Mervin King’s “Review of the Riksbank’s Monetary Policy 2010–2015.” The report criticizes monetary policy decisions after but not before 2011. It recommends a core inflation target, organizational changes and the possibility to suspend the inflation target.
Category Archives: Notes
Stable Inflation Expectations
In an Atlanta Fed blog post, Nikolay Gospodinov, Paula Tkac, and Bin We explain research suggesting that inflation expectations are stable, in spite of the rather dramatic drop in five-year/five-year forward TIPS breakeven inflation. They conclude:
To summarize, our analysis suggests that (1) long-run inflation expectations remain stable and anchored, (2) the seemingly large correlation of market-implied inflation compensation with oil prices arises mainly from the dynamics of the TIPS liquidity premium, and (3) long-run market- and survey-based inflation expectations are remarkably close in terms of level and dynamics over time.
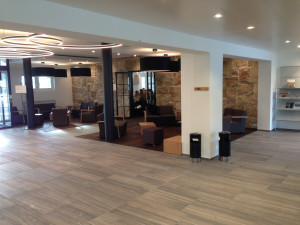
New Lobby of the Study Center Gerzensee
The restaurant building has been renovated; here is a picture of the new lobby.
Accounting for Leasing
In the FT, Kate Burgess, Harriet Agnew and Scheherazade Daneshkhu report about new accounting rules according to which companies will have to report leasing commitments as debt (and the leased assets as on-balance-sheet assets).
A new financial reporting standard — the culmination of decades of debate over “off-balance sheet” financing — will affect more than one in two public companies globally.
Retail, airline and hotel companies are expected to be affected most strongly.
David Bowie †
Quasi-Sovereign Debt
In the FT, Elaine Moore and Jonathan Wheatley report about the increasing importance of sovereign-backed corporate and other debt in emerging markets.
New figures from JPMorgan and Bond Radar show that issuance of quasi-sovereign bonds outpaced that of sovereign bonds in emerging markets last year, raising the stock of such debt from $710bn in 2014 to a record $839bn by the end of 2015. By comparison, the stock of all external emerging market sovereign debt stood at $750bn at the end of last year, according to JPMorgan.
Quasi-sovereign borrowers include firms that are owned in large parts or controlled by the state, as well as local governments. Although the liabilities of these borrowers may be explicitly or implicitly guaranteed by the state, the official public debt statistics typically do not account for them.
Banks’ Debt Valuation Adjustments Will End
In the FT, Ben McLannahan reports about a change in US accounting standards concerning the valuation of bank debt.
Under the rules in place since 2007
banks were allowed to use market prices when valuing their own debt, meaning they could book profits when their debt fell in value and losses when it rose.
Particularly during the financial crisis this led to sizable effects of swings in debt prices on bank profits. Under pressure from financial institutions, the Financial Accounting Standards Board “threw in the towel” and follows the International Accounting Standards Board which already backtracked in 2014. Under the new rules the debt valuation adjustments are expected to become more or less irrelevant.
The intention of the 2007 rules was clear:
… if banks were going to book their assets at market value, rather than cost, they should also book their liabilities at market value. Companies should therefore be allowed to recognise gains when the value of their bonds fell below par, the FASB reasoned, on the assumption that they would be able to buy them back at a discount.
But this implied that banks “booked income in bad times and expenses in good times.”
The Academic Ghostwriting Business
In the NZZ, Katharina Bracher reports about the flourishing ‘academic’ ghostwriting market in Switzerland. Firms like GWriters, Acad Write oder Acadoo offer ‘advice’ for Master and PhD theses writers. Demand is particularly high for law and business theses. A PhD thesis costs roughly CHF 25’000.
A German court has ruled that
das auftragsweise Erstellen von Hochschul-Abschlussarbeiten und Dissertationen zwar gegen die «guten Sitten» verstosse. Es handle sich aber «lediglich um ein rechtlich missbilligtes Gewerbe». Ghostwriting steht damit auf einer Stufe mit der Prostitution: zwar sittenwidrig, aber nicht verboten.
California

Arizona
Utah


Nevada

California
Liechtenstein Reforms Health Care Act
Voters in Liechtenstein rejected a popular initiative against the revision of the health care insurance act. The revision aims at keeping costs at bay.
The Fed Oversight Reform and Modernization (FORM) Act
On Econbrowser, Carl Walsh critically discusses H.R. 3189, The Fed Oversight Reform and Modernization (FORM) Act. He points out that the output gap measure in a policy rule plays an important role.
He writes:
Legislating a rule for the Fed’s instrument as a means of constraining its discretion and holding it accountable for its policy actions represents a fundamental shift from a policy such as inflation targeting. Under inflation targeting, the central bank is held accountable for meeting a target that represents an ultimate goal of monetary policy – low inflation – rather than for moving its policy instrument consistent with a specific rule. …
Using an estimated DSGE model, I find that the optimal weights to place on goal-based inflation and rule-based Taylor rule performance measures depend importantly on the output measure employed in the rule. When the rule is similar to that proposed recently in U.S. H.R. 3189, I find the optimal weight to assign to the rule-based performance measure is always equal to zero – that is, the rule H.R. 3189 proposed would lead to inferior macroeconomic outcomes and should not be used.
This result is largely driven by the fact that the definition of output used in the legislated rule – output relative to trend – is not consistent with the definition of output the theory behind the model I use would imply – output relative to its efficient level. When the Taylor rule is modified to use the measure of economic activity that is more consistent with basic macro theory, outcomes can be improved by making deviations from such the rule a part of a system for accessing the Fed’s performance and promoting its accountability.
Paris Climate Accord
In the NZZ, Markus Hofmann summarizes the agreement’s main points. The Guardian offers a series of reports as well as an analysis by Adam Vaughan.
Scent Culture
The Scent Culture Institute reflects on the sense of smell in culture, business and society.
Maps
Openstreetmap, the free, detailed map of the world.
Maps of Switzerland with a time shift function.
Previous posts: Animated historical maps; maps of WWI and WWII, German relative real estate prices, European population growth, and political risk.
Agreement on Net Financial Assets (Anfa)
In the FAZ, Daniel Plickert reports about a “secret” program of national central banks in the Euro zone to issue money. The Agreement on Net Financial Assets has been used since 2006 for securities purchases by national central banks, including the Bundesbank, Banque de France and Banca d’Italia.
Google does not find significant first hand online information about Anfa.
General Theory of Relativity Turns 100 (On Earth)
The Economist nicely discusses Einstein’s general theory of relativity. The article quotes John Wheeler’s dictum
Space-time tells matter how to move; matter tells space-time how to curve.
Drivers of High Skilled Migration into Switzerland
In the December Issue of Die Volkswirtschaft, Ronald Indergand and Andreas Beerli argue that increased high skilled migration into Switzerland mainly resulted from (i) higher educational attainment in the source countries and (ii) stronger demand by Swiss firms for high skilled labor.
The authors argue that the agreement between Switzerland and the European Union on the free mobility of labor (which is in force since 2002) did not contribute to an improved skill mix. Rather to the contrary, lower barriers to migration for EU citizens might have contributed to a slight reduction in the average skill of immigrants from the EU.
On the Benefits of Higher Inflation in Japan
In his blog, John Cochrane critically reviews arguments in favor of higher inflation in Japan.
He approves of the view that a conventional stimulus argument does not make much sense—given that Japanese growth is around potential and unemployment is low.
He does not approve of the view that inflation would be helpful by lowering (public and private) debt burdens. He doubts that an inflation induced default on outstanding debt would significantly lower taxes (rather than lead to more government spending) and that even if it did, such a default would increase the optimism of young households.
He also questions whether inflation could significantly reduce the real value of Japanese public debt (because debt maturity is short) and whether the debt burden is actually large (given near zero interest rates).
Health Care Costs and Benefits
This figure is taken from The Economist’s Graphic Detail blog.

Measuring (Greek) Indebtedness
In a Vox column, Daniel Dias und Mark Wright propose various measures of the Greek, Portuguese and Irish public debt burden and emphasize the large variability of these measures.
The following figure, taken from Dias and Wright, shows the scheduled principal and interest payments of Greece, Portugal and Ireland as a percentage of 2014 GDP in the respective country. Not all public debt components are accounted for.

Dias and Wright write:
[B]oth Portugal and Ireland face far larger cash flow requirements, relative to the size of their economies, than Greece for the next ten years. [A]fter this ten-year period, the required repayments on Greece’s debt will far exceed those of Portugal and Ireland, measured as a fraction of their economies. [W]hether or not we view Greece as more or less indebted than Portugal and Ireland depends on how we weigh cash flows in the near future (next ten years) versus cash flows in the far future (more than ten years).
… we can discount a country’s entire debt repayment cash flows by the interest rates embodied in their currently traded debts to obtain an estimate of the market value of a country’s debt. This assumes that the likelihood of repayment of Greece’s EFSF debt, for example, is the same as that for privately held bonds. Under these assumptions, as shown in Table 5, Greece appears to have less than half as much debt as either Portugal or Ireland. These numbers are closer to the estimates computed under the IPSAS standard, which records a debt at market value at the time of issue, and allows for the accretion of this debt if the contracted interest rate on the debt is less than the yield to maturity of the debt. This approach has the counterintuitive implication that the more likely a country is to default, the less indebted it will look.
Dias and Wright contrast a conventional face-value debt measure (the sum of the blue bars corresponding to principal repayment obligations in the figure) with more informative measures. With the latter, Greek indebtedness typically is not as high compared with the other countries as with the first measure.
See also this earlier post and this earlier post on the topic.